
What is Forced Liquidation Value (FLV)?
Forced Liquidation Value is the gross amount equipment would typically bring at a properly advertised public auction held on a short timeline, with the seller compelled to sell, the assets sold as-is and where-is, and the value stated as of a specific date. It is the most conservative of the common premises of value. Lenders use it to size the downside on a troubled credit, trustees and receivers use it to plan a disposition, and it appears in bankruptcy and creditor disputes. Lukes & Lukes is an independent machinery and equipment appraisal firm, and FLV is one of the premises we report for lenders, trustees and counsel nationwide.
By Jared Lukes · CEO & lead appraiser · September 11, 2026
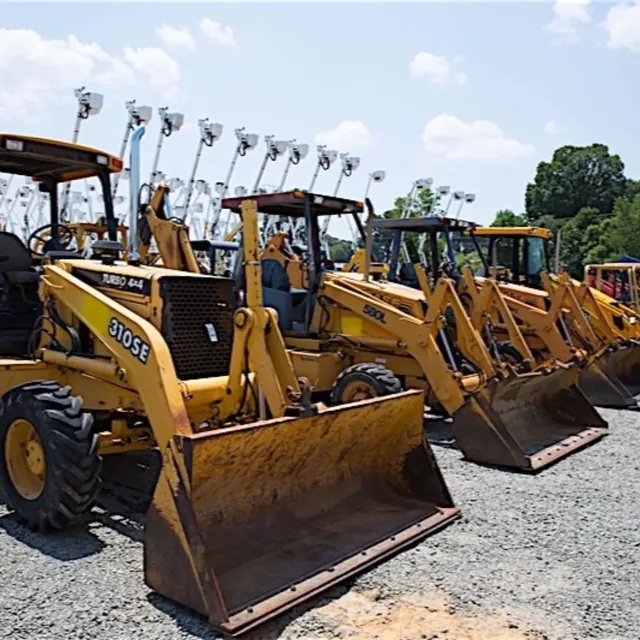
What does forced liquidation value mean?
Each part of the definition does work. Gross means the figure is the auction total before the costs of running the sale come out. Public auction means the assets are sold in one event to whoever attends or bids online, rather than placed one at a time with the best buyer. Compelled, with a sense of immediacy means the seller cannot wait for a better market, and every bidder knows it. As-is, where-is means no repairs, no warranty and no delivery: the buyer takes the equipment in its current condition and pays to remove it. As of a specific date means the number reflects the used-equipment market on that day.
Put together, FLV answers a narrow question: if this equipment had to be turned into cash quickly, in a single properly run auction, what would the bids total? That is a different question from what the equipment is worth to the business using it, and a different question from what a patient seller could get.
How FLV differs from OLV and NOLV
All three liquidation premises assume the seller is exiting. They differ in how much time the sale gets and whether the costs of selling are deducted.
- Orderly Liquidation Value (OLV): a compelled sale, but over a limited and reasonable period, typically measured in months, with time to market each asset through dealers, private sales and targeted auctions. The extra time reaches more buyers, so OLV sits above FLV.
- Forced Liquidation Value (FLV): a single, compressed auction event. Less time means fewer qualified buyers competing for each lot, so the number is lower.
- Net Orderly Liquidation Value (NOLV): OLV minus the costs of sale. NOLV is a net figure, where OLV and FLV are usually stated gross.
Some credit policies also ask for a net forced liquidation figure, with auction commissions, removal and site costs deducted from FLV. When they do, the report should say plainly whether the stated FLV is gross or net and list what came out, because an unlabeled number is easy to misread in the file. For every premise side by side, including Fair Market Value and replacement cost, see FMV, OLV, FLV and NOLV explained.
What drives the gap between forced and orderly value
The spread between FLV and OLV is not a fixed discount. It depends on how deep the auction market is for each class of asset and how much the short timeline costs.
- Depth of the buyer pool: common, portable equipment with a national auction following (construction equipment, forklifts, trucks, standard machine tools) draws competitive bidding even on short notice, so the spread is narrow. Specialized or single-purpose equipment may have a handful of real buyers, and a one-day sale may not reach them.
- Removal burden: the buyer of an installed line, a large press or a shielded imaging system pays for rigging, disconnection and freight. Bidders subtract those costs from what they will pay, which widens the spread on heavy and installed assets.
- Volume on one sale: twenty similar machines offered in one afternoon compete with each other, and the later lots often bring less than the first.
- Timing: farm equipment buyers are most active in the months before planting, so a sale forced into the middle of harvest meets fewer of them. A sale timed into a soft market for a class brings less than the same sale in a stronger one.
- Condition and documentation: as-is means bidders price the risk of what they cannot verify. Equipment with maintenance records, hour readings and a clean inspection closes more of the gap than equipment that cannot be run.
When lenders, trustees and courts use FLV
- Troubled credits and workouts: when a loan moves to special assets, the question changes from what the collateral supports to what it would bring if the lender had to take it. FLV sets the floor for that conversation. See liquidation and auction appraisals.
- Downside underwriting: some lenders ask for FLV alongside OLV or NOLV at origination to see the worst case on specialized equipment. More on how we support lenders and credit teams.
- Bankruptcy: liquidation analyses, adequate-protection disputes and trustee dispositions often turn on what the equipment would bring in a quick sale. See equipment appraisal for litigation.
- Receiverships and assignments for the benefit of creditors: a receiver or assignee planning a sale needs a realistic expectation before choosing how to sell.
- Settlement negotiations: a borrower negotiating a payoff or a voluntary surrender of the collateral uses FLV to show what the lender would net by forcing a sale.
An appraisal of FLV is not an auctioneer's estimate
Auction companies give estimates, and a good auctioneer knows the market. The estimate is still written by a party that earns a commission if it gets the sale. An appraisal of forced liquidation value is an independent opinion prepared under USPAP by an appraiser with no stake in which sale method is chosen or who runs it. That independence is what lets the number sit in a credit file or a court record. The same distinction applies to a broker opinion of value.
FLV is also an opinion as of a date under stated conditions, not a promise of results. Actual auction proceeds depend on the day, the marketing and the crowd. A defensible appraisal states its assumptions so a reader can see what would move the number.
What a defensible FLV report shows
USPAP requires a personal property appraisal report to state the type and definition of value and cite the source of the definition. For FLV, that means the report names the premise, gives the definition it relies on, and states the assumed sale conditions: the timeline, the venue and whether costs of sale are deducted. Beyond that, the reader should find:
- Auction evidence for each class of asset, with sale dates and venues, rather than a flat percentage applied to cost or to fair market value
- Equipment observed on site, with make, model, serial number, hours and condition recorded per unit
- The adjustments between the comparable sales and the subject equipment, written out
- An appraiser who is independent of the borrower, the lender and the eventual sale
Our reports are USPAP-compliant and prepared by a NEBB-certified Machinery & Equipment Appraiser (CMEA). When a file needs more than one premise, FLV, OLV and NOLV can be carried side by side in the same report, each with its own support.
Common questions
Answers, up front.
What does FLV stand for?
Forced Liquidation Value. It is the gross amount equipment would typically bring at a properly advertised public auction held on a short timeline, with the seller compelled to sell and the assets sold as-is, where-is, as of a specific date.
Is forced liquidation value always lower than orderly liquidation value?
Almost always. Both assume a compelled seller, but OLV allows a limited and reasonable period to reach buyers, while FLV assumes a single compressed auction. Less time reaches fewer bidders. The spread is narrow for common, portable equipment and wide for specialized or installed equipment.
Is FLV a gross or a net figure?
Usually gross: the expected auction proceeds before commissions, removal and other costs of sale. Some lenders ask for a net forced liquidation figure with those costs deducted. The report should state which one it gives and list any deductions.
When does a lender ask for FLV?
Most often when a credit is troubled or in workout, to see what the collateral would bring in a quick sale. Some lenders also request FLV at origination for specialized equipment, alongside OLV or NOLV, to understand the worst case.
Is forced liquidation value the same as auction value?
Close, but not the same. FLV is an appraiser's opinion of what a properly advertised, compelled auction would bring as of a date, built from comparable auction results. An actual auction outcome depends on the day, the marketing and the bidders, and an auctioneer's estimate comes from a party with a stake in the sale.
How is forced liquidation value determined?
Primarily by the sales comparison approach: recent auction results for comparable equipment, adjusted for age, condition, configuration, hours, location and the timing of the sale. The appraiser inspects the equipment, identifies each unit and documents the evidence behind every conclusion so a lender or court can trace it.